
Can a Verbal Loan Be Enforced? Why a Handshake Usually Falls Apart
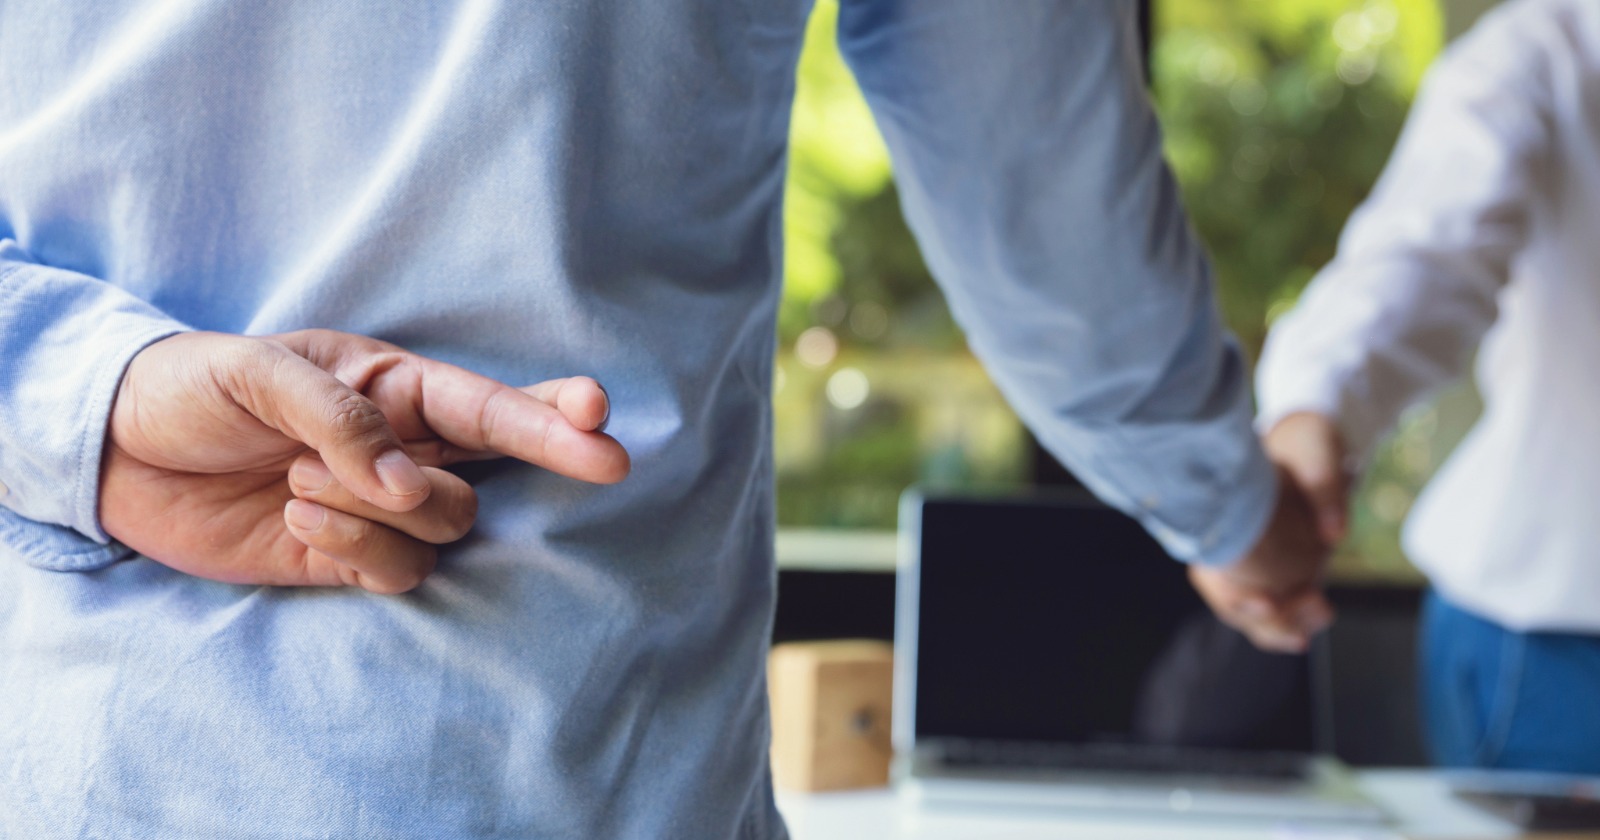
When you lend money on a promise and a handshake, you have made a verbal contract, and in most situations that agreement is legally valid. The trouble is not usually whether the law recognizes your loan. The trouble is that months later, when the money has not come back, you have to prove three things a court will insist on: that you handed over the money, that the other person agreed to repay it, and on what terms. A handshake gives you none of that in writing, and that is where good intentions come apart.
Legal and provable are two different questions
It helps to separate two ideas that people tend to blur together. The first is whether an oral loan is legal, and for ordinary personal loans the answer is generally yes. The second is whether you can prove it if the borrower denies the debt or disputes the terms. That second question is where verbal loans collapse. A judge cannot enforce what cannot be established, and your memory of the conversation, however honest, carries far less weight than a signed document that spells out the deal. You may be completely right about what was agreed and still lose because you cannot show it.
When the statute of frauds demands a writing
Every state has a version of the statute of frauds, a rule that requires certain contracts to be in writing and signed to be enforceable at all. According to the Cornell Legal Information Institute (LII), the categories that most often reach into loans include agreements for the sale or transfer of land and agreements that by their terms cannot be completed within one year. So if you lend money and the repayment schedule stretches beyond a year, the safest reading is that the promise needs to be written down. A purely oral multi-year loan may be unenforceable no matter how clearly you both remember agreeing to it.
The one-year trap
The one-year provision surprises people. It does not turn on how long the loan actually runs. It turns on whether the agreement, by its own terms, could possibly be performed within a year. A loan due on demand or repayable within twelve months usually falls outside the writing requirement. A loan you both understood would be paid back over three years usually falls inside it. When you are not certain which side of that line your arrangement sits on, treating the loan as one that must be written down is the cautious and sensible choice, because the cost of a short document is nothing next to the cost of an unenforceable promise.
Proving a verbal loan when it goes wrong
Suppose the statute of frauds does not apply and your oral loan is enforceable in principle. You still have to prove it. People try to reconstruct the deal from whatever exists: a bank record or transfer showing the money moving, text messages or emails where the borrower acknowledges the debt or promises to pay, and testimony from anyone who witnessed the arrangement. Those pieces can carry the day, but they are scattered, they are open to interpretation, and the borrower can offer an innocent explanation for each one. You are asking a court to assemble a contract you never wrote, one fragment at a time.
Partial performance can help, but it is fragile
Courts sometimes recognize that conduct can back up an unwritten deal. If the borrower made a few payments before stopping, those payments are powerful evidence that a loan existed, because people do not usually repay gifts. A written acknowledgment of the debt, even a casual one in a text, can revive or confirm an obligation. But leaning on partial performance is a gamble. It depends on the borrower having done something that only makes sense if a loan was real, and on a judge agreeing to read it that way. You do not want your recovery to hinge on whether an old text message says enough.
The gift-versus-loan fight
The most bruising dispute in verbal lending is the one that erupts inside families. You transferred money to help someone you love, fully expecting it back. When you ask for repayment, you hear that the money was a gift. Without a writing, that argument is genuinely hard to defeat, because a transfer between family members looks the same whether it was a loan or a present. The law will often ask what the parties intended, and intention with no document behind it becomes one person's word against another's, at exactly the moment the relationship can least afford it.
The statute of limitations is quietly running
There is one more reason a handshake is dangerous, and it works against the lender even when the loan is real. Every state sets a statute of limitations, a deadline after which a debt can no longer be enforced in court. For oral contracts that window is often shorter than it is for written ones, sometimes by years. So the person who lends on a promise not only has a harder time proving the debt, they may also have less time to sue before the right to collect lapses entirely. A borrower can simply wait you out. A written note, by contrast, usually carries the longer limitations period and starts from a date you can point to on the page.
The fix is a written promise
You do not need a lawyer in the room to protect a loan. A promissory note converts a fragile verbal understanding into a signed, dated record that names the amount, the repayment terms, and the interest, if any. It answers the questions a court asks before you ever reach a court. It settles the gift-versus-loan question in advance, in writing, while everyone is still on good terms. And it does something quieter and just as valuable: it lets you help someone with money without letting the money quietly damage the relationship. Choosing the right form, whether a demand note or a scheduled one, takes minutes and spares you the argument that verbal loans almost always invite.
Sources
James Stackpoole is a personal finance writer who covers lending, contracts, and everyday legal documents. He focuses on making complex financial topics approachable for borrowers and lenders navigating agreements outside of traditional institutions.
View all posts →Create Your Promissory Note
Need a promissory note? Create one now for $7.99 - state-specific and professionally formatted.
Get Started - $7.99